The Valuation Gap Nobody's Talking About
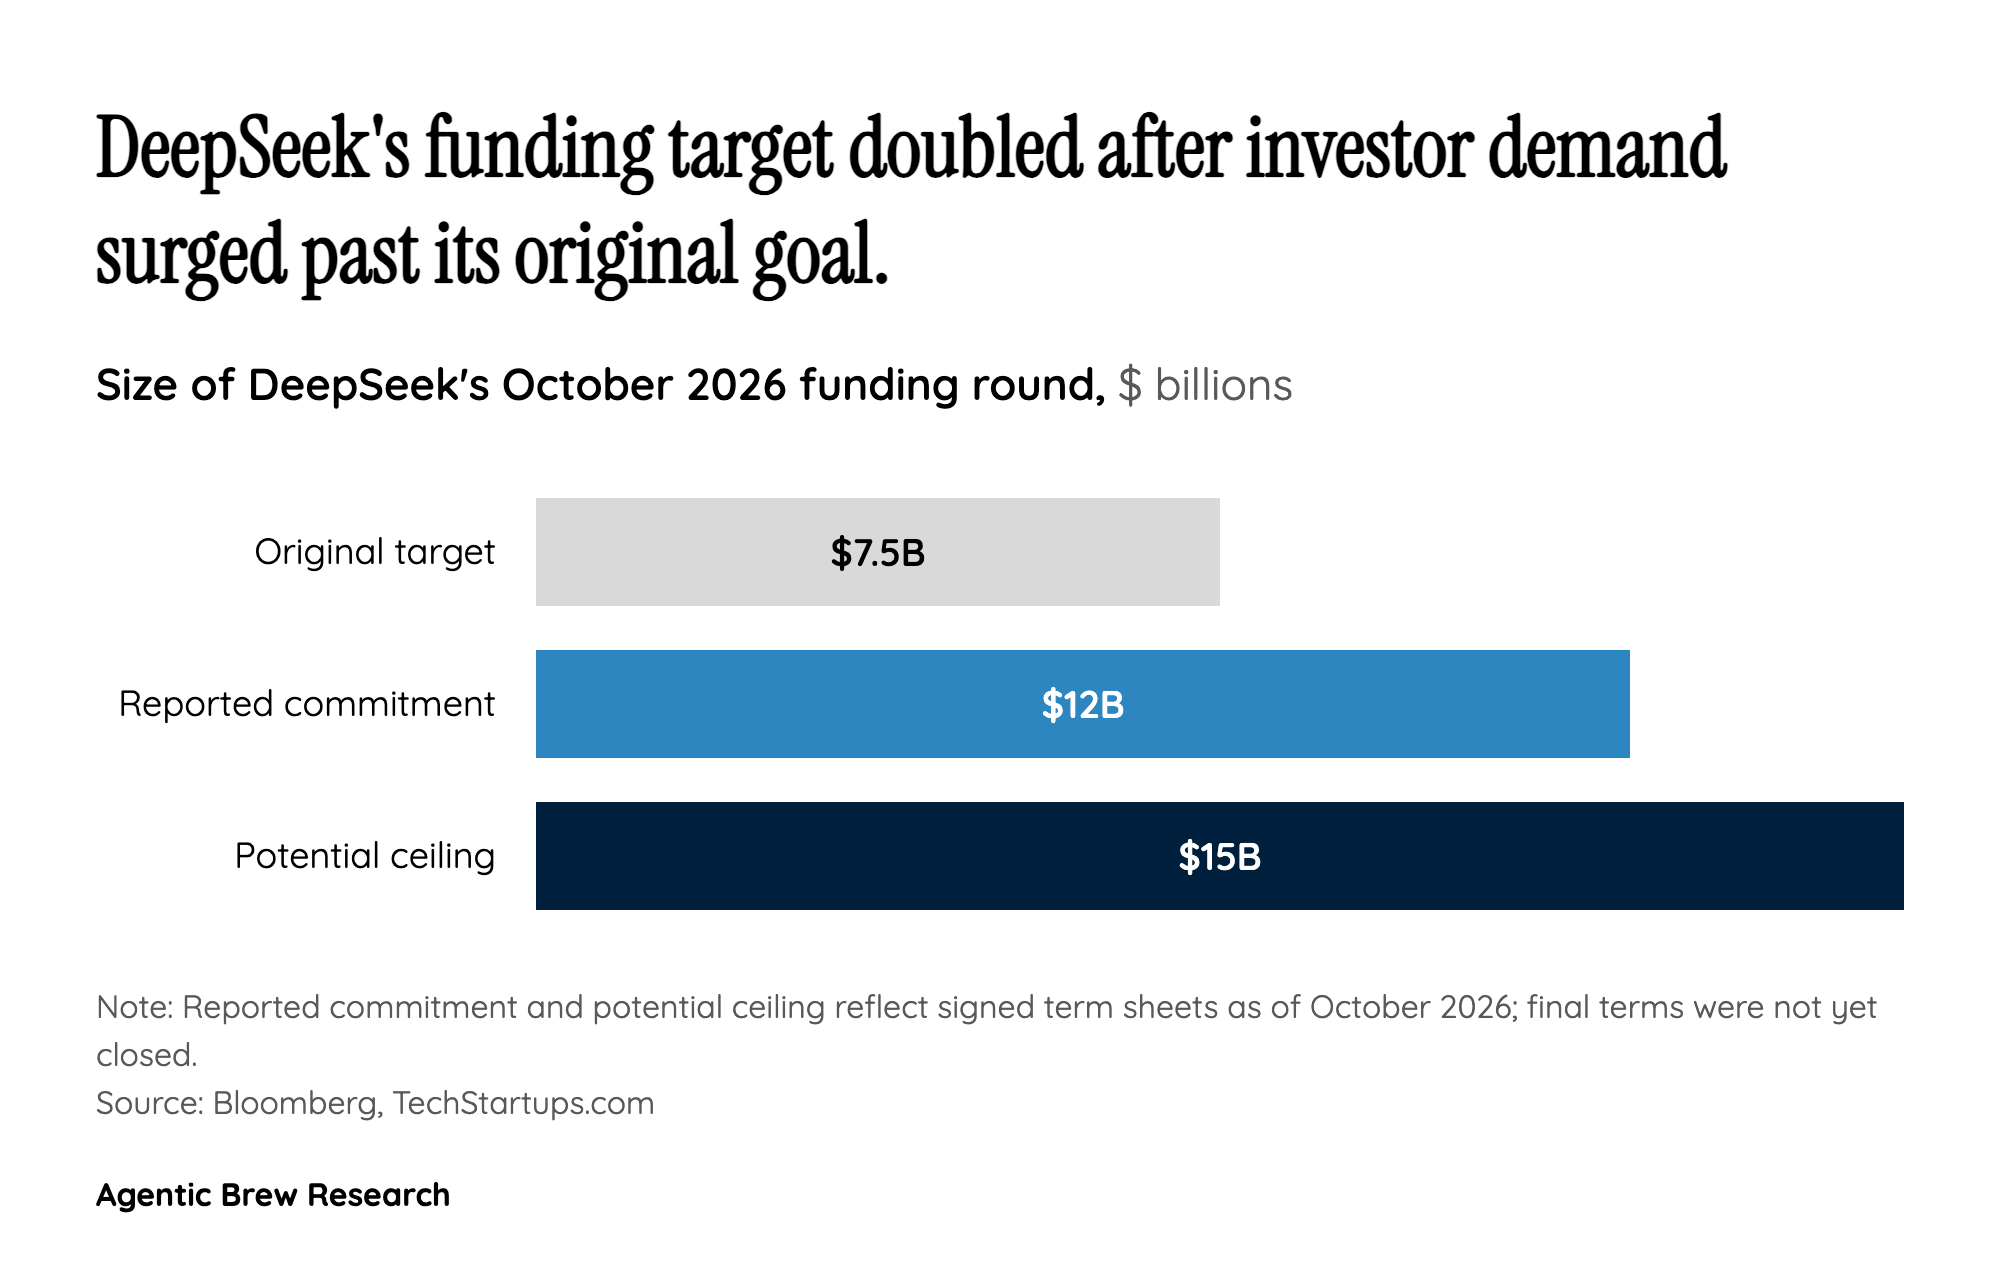
If DeepSeek's round closes near its upper range, the implied valuation lands around $75 billion - a fraction of OpenAI's reported $1.4 trillion target in its concurrent $30 billion raise. That gap is notable given both companies are chasing the same thing: capital to buy compute and fund a landmark IPO. Market commentary around the deal has floated two competing explanations - either a persistent discount on Chinese AI assets, or inflation in US valuations - and it is genuinely unclear which read is correct.
The skepticism around pricing predates this round. Kevin Xu, founder of Interconnected Capital, has argued that DeepSeek already proved Chinese labs can build frontier models despite export-control constraints [1], which cuts against the idea that a lower valuation reflects lower technical capability. PitchBook's Melanie Tng goes further, arguing DeepSeek's cost-efficient approach to model-building challenges the sustainability of billion-dollar training budgets elsewhere [2]- which would mean the "discount" is DeepSeek undercutting the price of frontier AI, not trailing it.